World Center for Strategic Studies
From closed analysis to public debate
- MONTH
- YEAR
France’s Debt Trap Is Tightening: Paris Could Become Too Big to Rescue
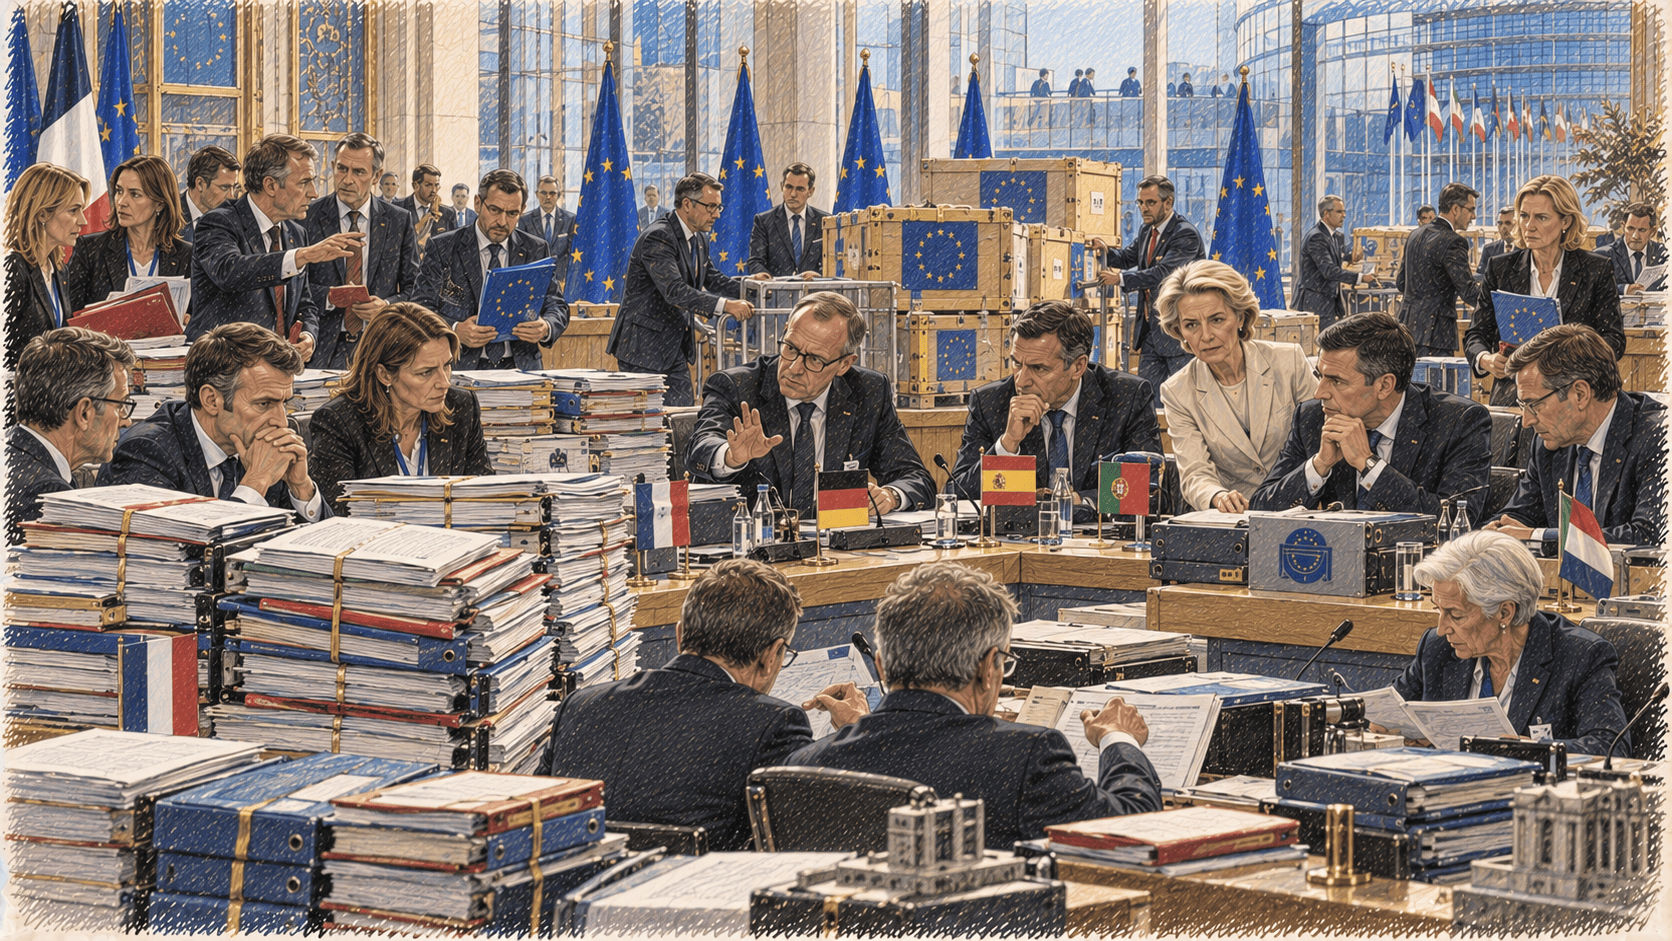
France is running out of room to escape its public-finance crisis. With the deficit reaching 5.4% of GDP and public debt approaching 120%, rising borrowing costs are turning years of fiscal complacency into an increasingly dangerous liability. Institut Montaigne economist Olivier Garnier warns that France is becoming one of the weakest links in European sovereign-debt markets, where investors punish vulnerable borrowers first. The government's 2027 budget promises €54 billion in fiscal adjustments, but even that would leave a deficit of 5% of GDP. The uncomfortable possibility is that France may be too large for its European partners to rescue – and too politically divided to repair its finances quickly.
The deficit keeps escaping control
France's fiscal projections are deteriorating faster than governments can correct them.
The expected 2026 deficit has been revised from 5% to 5.4% of GDP, partly because economic growth has been downgraded from 1% to just 0.5%.
Without new measures, the 2027 deficit would reach 6.5% of GDP. By 2030, it could approach 7%, pushing public debt beyond 130% of GDP.
The proposed €54 billion adjustment would reduce the 2027 deficit to 5%, but that remains far above the EU's 3% reference level.
France never reversed its borrowing addiction
Garnier identifies a structural weakness that distinguishes France from many European neighbours.
After the global financial crisis and the pandemic, public debt jumped across Europe. But other countries subsequently reduced their deficits or debt ratios.
France failed to reverse those increases.
Between 2000 and 2023, its debt ratio rose by approximately 50 percentage points of GDP, compared with around 20 points across the eurozone.
The main culprit was not exceptional economic shocks or rising interest rates, but the persistent accumulation of structural primary deficits.
Cheap money concealed the danger
For years, falling interest rates allowed France to accumulate debt without facing an immediate explosion in financing costs.
In the 1990s, interest payments consumed roughly 3.5% of GDP when debt stood near 60%.
Today, despite debt being approximately twice as large relative to GDP, interest costs remain around 2.6%.
That financial advantage is disappearing as borrowing costs rise.
France can no longer assume that economic growth and favourable interest rates will quietly absorb its deficits.
The arithmetic is becoming brutal
Garnier calculates that France's primary deficit is currently close to 3% of GDP.
Yet stabilising debt near 130% of GDP by 2032 would require a primary surplus of approximately 1%.
That implies a fiscal adjustment of at least four percentage points of GDP merely to stop the debt ratio rising.
The problem is therefore considerably larger than the adjustments proposed in a single annual budget.
European rules offer no easy escape
The EU's revised fiscal framework gives countries greater flexibility but also imposes expenditure limits tailored to their financial circumstances.
France is under an excessive-deficit procedure, with recommended annual growth in net primary expenditure capped at 1.2%.
Its 2027 budget proposal meets that ceiling, but the 2026 increase is expected to reach 1.4%.
Compliance matters because it is a necessary condition for access to the European Central Bank's Transmission Protection Instrument.
But Garnier warns that the ECB cannot be expected to rescue a government whose borrowing costs rise because it refuses to restore fiscal sustainability.
A constitutional rule would not solve the crisis
Some French politicians advocate placing a balanced-budget rule in the constitution.
Garnier questions whether such a measure would work when France has repeatedly failed to respect existing European commitments.
A constitutional rule would still need exceptions for defence spending, economic emergencies and other circumstances.
More importantly, it would not explain how France should move from its present enormous deficit towards sustainable finances.
The missing ingredient is credible political commitment, not another legal formula.
Markets could force Paris to act
The approaching presidential election adds another layer of uncertainty.
Garnier expects pressure on the spread between French and German government bonds to intensify as investors struggle to identify a credible post-election fiscal strategy.
Rising global interest rates could make matters worse, because weaker sovereign borrowers tend to suffer first when financial conditions tighten.
France cannot assume that its economic size guarantees protection.
Its debt may instead be too large for a straightforward European bailout.
The stark truth: France must repair its finances itself
Garnier rejects comparisons with Greece's debt crisis. France still has the economic capacity to restore fiscal sustainability, as demonstrated by its adjustment before joining the euro and by more recent reforms in Spain and Portugal.
But the required effort is substantial, and France's European partners have little reason to finance a country whose public spending is already much higher than theirs.
The danger is not that France has no way out. It is that political paralysis and rising borrowing costs could make every delay more expensive.